A roof insurance claim in Florida lives or dies on documentation. When storm damage is photographed thoroughly, scoped in the software adjusters use, and presented clearly, the claim has its best chance. When it is vague or undocumented, it stalls or gets denied. As a Florida state-certified, insured roofing contractor, we handle the roofing side of that process: the drone damage report, the line-item estimate, and meeting your adjuster on the roof. Call (831) 666-1600 to get the documentation started.
One honest thing up front: we are your roofing contractor, not your insurance company or a public adjuster. We document what the storm actually did and estimate what it will cost to repair to code, but we cannot promise your carrier will approve the claim or how much they will pay. What we can do is make sure the roofing evidence is complete and accurate so the decision is made on facts. For how the process works end to end, see our guide on how a roof insurance claim works in Florida.
Signs you need insurance claims in Boca Raton
Damage that is hard to see from the ground
Wind and hail damage on tile and flat roofs is often invisible from the driveway. Without a proper inspection, real damage goes undocumented and unclaimed.
Vague or lowball estimates
A one-line estimate gives an adjuster nothing to work with. Claims move when every item, from underlayment to flashing to code upgrades, is scoped and priced.
Missed deadlines and paperwork
Florida has firm timelines for reporting storm damage, and missing them can end a claim before it starts. The paperwork has to be right and on time.
Confusion over what is covered
Sudden storm damage is generally claimable; long-term wear and age usually are not. Knowing the difference before you file saves a wasted claim on your record.
Our process
- 1
Drone inspection and damage report
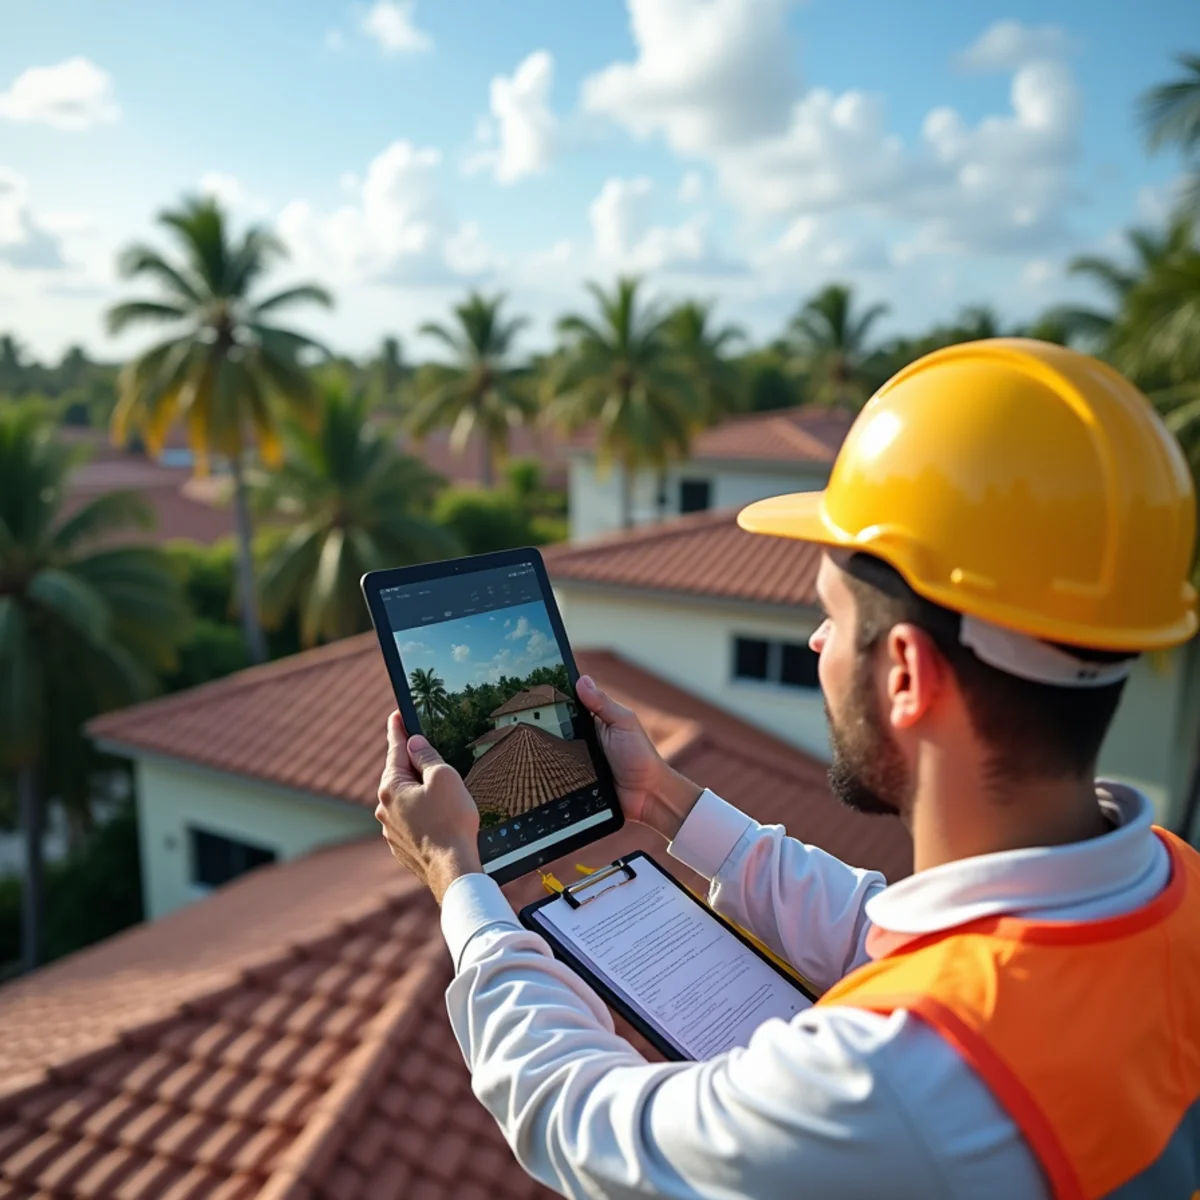
We fly the roof and produce a dated, detailed photo report of the storm damage. Our <a href="/drone-roof-inspection/">drone roof inspection</a> captures what a ground look misses, before anything is disturbed.
- 2
Storm-documentation checklist
We work through a storm-documentation checklist: date of loss, photos of every damaged area, interior water damage, and the emergency mitigation you took, so nothing that supports the claim is left out.
- 3
Insurer-standard estimate
We write a line-item estimate in the software adjusters use, covering tear-off, underlayment, flashing, decking, code upgrades, and cleanup, so it can be compared directly to the carrier's numbers.
- 4
Adjuster meeting on the roof
We meet your adjuster on site and walk the damage together, pointing out what they may not catch from the ground and answering questions about repair-to-code requirements.
- 5
Repair or replacement once approved
After you and your carrier settle the claim, we complete the <a href="/hurricane-roof-damage-repair/">storm damage repair</a> or full <a href="/roof-replacement/">replacement</a> to the 2023 Florida Building Code and hand off the paperwork.
What a roofing contractor can and cannot do on your claim
It matters that you understand the roles. We are the roofing contractor. We inspect the roof, document the damage, and write an accurate estimate to repair it to code, and we will stand behind that scope when the adjuster is on the roof. What we cannot do, and what you should be wary of anyone promising, is guarantee that your claim will be approved, tell you the damage is covered before your carrier rules, or handle the claim negotiation for you the way a licensed public adjuster does.
If a company knocks on your door after a storm promising to get your claim approved, waive your deductible, or handle everything so you pay nothing, treat that as a warning sign. Waiving deductibles is illegal in Florida, and those promises usually come from crews that will not be here for the warranty. Verify any contractor's license at myfloridalicense.com, where certified roofing licenses begin with CCC.
The storm-documentation checklist that supports a claim
Good claims are built before the repair, not after. As soon as it is safe, record the date of the storm and photograph everything: each damaged slope, missing or cracked tile, lifted flashing, and any water that came inside, including stained ceilings and soaked belongings. Keep receipts for the emergency tarping or dry-in you had done, because that mitigation is both required by your policy and reimbursable. Do not throw away damaged materials until they are documented.
We bring this together into a single dated report and a line-item estimate your adjuster can review. Filing has deadlines in Florida, so start early. Our guides on how a claim works and the 25% roof rule explain the timeline and the code requirements that shape the final scope.
Insurance Claims across Palm Beach & Broward County
We document roof insurance claims for homeowners across Palm Beach and Broward. That includes drone damage reports and adjuster meetings in Boynton Beach, Delray Beach, and Lake Worth Beach in Palm Beach County, and in Deerfield Beach, Coral Springs, and Parkland in Broward. From our N Federal Highway office we can meet most adjusters same-day or next-day.
The county line shapes the estimate. When repairs cross Florida's 25% threshold, a Broward roof has to be rebuilt to High-Velocity Hurricane Zone standards with NOA-approved products, which changes the code-upgrade line items an adjuster reviews. Palm Beach County roofs are outside the HVHZ and rebuild under Florida Product Approval. We scope whichever applies honestly: we document the damage and estimate the repair to code, but the carrier decides whether and how much to pay.
What affects your price
Documenting damage and estimating the repair is part of how we earn the job; we are transparent that we are a contractor, not a claims adjuster. The repair itself is priced from the approved scope and your policy's deductible.
- Your deductible
- Florida hurricane deductibles are often a percentage of the dwelling coverage, which can be several thousand dollars, and that is your out-of-pocket share.
- Recoverable depreciation
- Many policies pay actual cash value first and release the held-back depreciation after the work is completed and invoiced.
- Scope of covered damage
- What the carrier agrees the storm caused, versus pre-existing wear, sets how much of the roof the claim pays for.
- Code-upgrade coverage
- Some policies include law-and-ordinance coverage that pays for the code upgrades the 25% rule can require; whether yours does affects the total.
- Repair versus replacement
- An approved repair costs less than a full replacement, but the 25% rule may require replacing an entire section to current code.
These are honest planning ranges, not a quote. Your written scope confirms the real price after a free inspection. Call (831) 666-1600.
Why choose Mighty Dog Roofing for insurance claims
- Detailed drone damage report, dated and complete, before anything is disturbed
- Line-item estimates written in the software adjusters actually use
- We meet your adjuster on the roof and walk the damage together
- Honest about what we can and cannot do: we document, we do not decide the claim
- Florida state-certified, insured contractor, verifiable at myfloridalicense.com
- A clear handoff from approved claim to code-compliant repair or replacement